
The Ghana Revenue Authority (GRA) has moved to dispel widespread confusion over the treatment of mobile phones at the country’s entry points, insisting there is no law capping travellers at two duty-free devices.
According to the Authority, Customs officers do not apply a fixed numerical limit. Instead, they assess whether the phones and other goods a traveller is carrying are genuinely intended for personal use or amount to a commercial import in disguise.
The clarification was made by Elsie Appau-Klu, Technical Advisor to the Commissioner-General of the GRA, on Joy News’ The Law programme on Sunday, September 13.
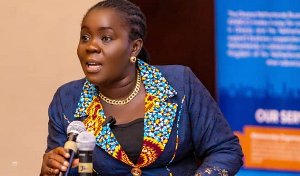
She explained that an earlier comment by the Commissioner of Customs, Aaron Kanor, referencing travellers carrying “two phones,” had been widely misread as a statutory threshold.
“There is no law that says two phones and no more,” she stated.
Ms Appau-Klu stressed that the sheer number of phones carried does not, on its own, determine whether duty is payable. The reference to one phone for the traveller and another for a spouse, she said, was meant only to illustrate the principle of personal use — not to announce a new tax rule.
The GRA had already sought to clear the air on September 3, stating that carrying more than two mobile phones does not automatically make a traveller liable to pay duty. Rather, Customs weighs the nature, condition and quantity of the items against the circumstances of their importation.
Advertisement
That assessment could turn on whether the devices are used or brand-new, whether they remain in commercial packaging, and whether several identical phones are being carried at once. A traveller with a personal phone and a separate work device, for instance, presents a very different profile from someone carrying multiple identical handsets still sealed in their boxes.
Ms Appau-Klu anchored the practice in Ghana’s customs and exemptions framework. Section 107 of the Customs Act, 2015 (Act 891), provides duty concessions on qualifying personal and household effects, while Section 17(1) of the Exemptions Act, 2022 (Act 1083), grants exemptions on qualifying accompanying baggage, subject to conditions.
Advertisement
She also cited Regulation 18(2)(b) of the Exemptions Regulations, 2025 (L.I. 2514), which empowers the Commissioner-General to determine the quantity of accompanying baggage that qualifies for the passenger exemption. That power, she maintained, does not amount to creating a new tax or imposing a numerical cap outside the law.
The matter has nonetheless attracted fresh scrutiny after a constitutional challenge to Regulation 18(2)(b) was filed at the Supreme Court. The challenge contends that the provision could effectively confer a power to waive or vary taxes — something that, under Article 174(2) of the 1992 Constitution, requires prior parliamentary approval. The Supreme Court is expected to rule on that question.
For now, the GRA insists Customs is simply applying an existing legal standard rather than enforcing a so-called “two-phone” rule. Ms Appau-Klu advised travellers who are unsure about the status of the goods they are carrying to declare them properly and seek clarification from Customs officers.